The Broadway theater industry faced a challenging week as box office returns experienced a notable decline for the period ending November 1, signaling a potential cooling trend in the highly competitive 2026-27 season. Total box office receipts for the 33 active productions reached $29,572,284, a contraction of approximately 13% when compared to both the preceding week and the corresponding period from the previous season. This downturn, which saw 26 of the 33 running shows report lower figures, has prompted industry analysts to examine the confluence of seasonal shifts, regional cultural events, and evolving consumer spending habits.
A Seasonal Shift in Theater Attendance
Industry observers have pointed to the late-October timeframe as a historically volatile period for live entertainment. The week in question included Halloween Saturday, an evening traditionally marked by increased urban activity centered on nightlife and non-theatrical celebrations, which may have siphoned off potential ticket buyers. Attendance figures reflected this wider malaise; the total count of 251,700 patrons represented a 4% decline week-over-week and a more concerning 9% drop compared to the same week last year.
The economic impact was not distributed evenly, but it was widespread. Two notable productions, & Juliet and The Outsiders, bore the brunt of the market softening. Both shows saw their weekly grosses diminish by more than $300,000, bringing their respective totals to $610,232 and $605,946. While such fluctuations are common in the cyclical nature of Broadway, the simultaneous decline across such a high percentage of the roster suggests a broader macroeconomic or behavioral shift in the New York City theater-going demographic.
The Premium Tier: Ticket Pricing Analysis
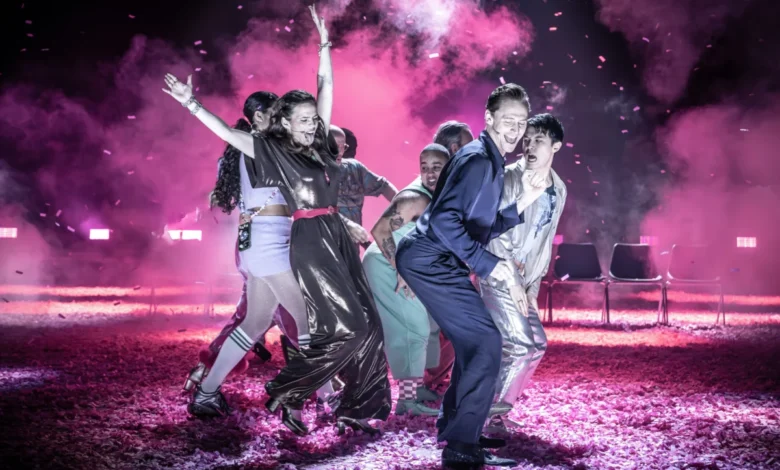
Despite the general contraction in revenue, the premium segment of the market remained resilient. An analysis of the data provided by The Broadway League reveals that certain productions command significant price premiums regardless of broader market trends. Other Desert Cities led the ticket price roster, maintaining an average paid admission of $301.23. This figure underscores a continued willingness among a segment of the audience to pay a premium for high-demand, star-studded, or critically acclaimed productions.
Only two other productions managed to break the $200 average ticket price threshold during this period: the long-running phenomenon Hamilton, which maintained an average of $218.03, and the revival of Much Ado About Nothing, which held steady at $238.36. The overall average paid admission for all 33 shows settled at $117.49. This metric serves as a vital barometer for the industry, indicating that while total volume is down, the baseline cost of entry for a Broadway experience remains firmly entrenched in the triple digits, a factor that continues to weigh on the accessibility of theater for the average consumer.
The Impact of New Productions and Previews
The theater district’s vitality is often measured by the influx of new work, and last week was no exception. Three productions were in the preview stage, providing a necessary injection of interest into the marketplace. Of particular note was Billy Crystal’s 860, which, despite having three performances heavily comprised of industry-comped press tickets, still managed to generate an impressive $1,353,611 over seven performances. With an attendance rate of 99%, the production demonstrated that star power and high-concept programming remain the most effective tools for bucking downward market trends.
The success of 860 highlights a recurring theme in contemporary Broadway business: the reliance on established names to anchor a season. As legacy shows begin to see their audiences plateau, producers are increasingly looking to limited-run engagements featuring well-known actors to bridge the gap between blockbuster hits and experimental off-Broadway transfers.
Season-to-Date Contextualization
To understand the current slump, one must look at the broader context of the 2026-27 season. We are currently in the 23rd week of the season, and the cumulative gross sits at $726,010,709. This figure represents an 8% decline compared to the same point in the 2025-26 season. Similarly, total attendance has reached 5,929,169, which is 3% lower than the comparative year-to-date figure.
These statistics offer a sobering look at the industry’s trajectory. While the post-pandemic rebound saw a massive surge in demand as patrons returned to theaters, the current phase appears to be one of correction. The industry is currently contending with several headwinds: inflationary pressures affecting production costs, increased competition for leisure time, and a changing tourist landscape.
Implications for Producers and Stakeholders
The financial data, compiled and disseminated by The Broadway League, provides the essential foundation for understanding these trends. For producers, the primary challenge is determining whether the current slump is a transitory "Halloween effect" or a signal of deeper resistance to rising ticket prices.
Financial analysts often suggest that when attendance drops alongside revenue, it is indicative of a "price-sensitivity threshold" being breached. If the average ticket price continues to rise while the number of available seats remains constant or increases, the eventual result is a decline in occupancy rates. The fact that 26 shows reported downturns suggests that theater owners and producers may soon need to recalibrate their dynamic pricing models to stimulate demand.
Furthermore, the industry is closely watching the performance of the current preview slate to determine how the spring season will shape up. If new shows continue to report high occupancy rates despite the broader market dip, it suggests that the problem is not a lack of interest in theater, but rather a lack of compelling content currently on the boards.
Industry Outlook and Future Trends
As we move toward the holiday season, Broadway typically experiences a "Thanksgiving bump," where increased tourism and seasonal theater-going behavior often offset the autumn lows. Industry insiders are looking to the upcoming influx of winter releases to revitalize the box office. Historically, the period between Thanksgiving and New Year’s Day is the most lucrative window for Broadway, often generating record-breaking weekly grosses that can pull a season’s total performance back into positive territory.
However, the current deficit of 8% in gross revenue creates a steep hill to climb. To reach the benchmarks of previous record-breaking seasons, Broadway will need not only a strong holiday performance but also a sustainable uptick in both tourism and local patronage throughout the first quarter of the coming year.
The Broadway League, which serves as the national trade association for the Broadway industry, continues to monitor these trends closely. Their data remains the gold standard for theater owners, investors, and stakeholders who rely on these figures to make critical decisions regarding marketing budgets, show longevity, and touring schedules. For those interested in the granular breakdown of individual show performances, the League’s official archives provide an exhaustive look at the weekly fluctuations that define the life and death of productions on the Great White Way.
In summary, while last week’s figures were disappointing for many producers, they are best viewed as part of a larger, evolving story. Broadway remains a high-stakes, high-reward industry where the line between a profitable hit and a costly closure is razor-thin. The coming weeks will be critical in determining whether this slump is a temporary deviation or a sign of a new, more challenging economic reality for the theater industry in New York. As the season progresses, the focus will undoubtedly remain on balancing the premium pricing necessary to sustain large-scale productions with the need to keep theater accessible to a broad and diverse audience.