The enduring landscape of physical video game media finds itself at a profound crossroads as traditional manufacturing ecosystems contract, leaving console manufacturers and third-party publishers to navigate a complex matrix of rising production costs, shifting consumer preferences, and technological evolution. While industry competitors such as Sony have progressively phased out physical game discs in certain sectors of their business, Nintendo has consistently reaffirmed its commitment to cartridge-based distribution. However, this dedication to tangible media is not without its operational challenges. Recent developments within the semiconductor supply chain, coupled with shifting economic pressures and fluctuating consumer adoption rates, suggest that the path forward for physical Nintendo cartridges will require careful navigation by the Kyoto-based gaming giant and its publishing partners alike.
At the heart of the current manufacturing dilemma is a shrinking pool of specialized component suppliers. As the global microelectronics market evolves and major semiconductor foundries reallocate their production lines toward higher-margin components such as automotive chips, artificial intelligence processors, and advanced mobile architectures, legacy production lines are increasingly being phased out or repurposed. For Nintendo, this industrial transition means that the production of the specialized Read-Only Memory (ROM) chips required for its game cartridges is becoming increasingly constrained.
Industry analysts point out that Nintendo is forced to rely on a diminishing roster of specialized suppliers—such as Rohm and Lapis Semiconductor—to secure the silicon wafers and memory components necessary to sustain its physical software ecosystem. Because ROM chip manufacturing for gaming cartridges occupies a specialized niche distinct from standard flash memory or dynamic random-access memory (DRAM), production lines are less flexible. Consequently, any disruption, capacity constraint, or operational pivot by these remaining primary suppliers directly translates to upward pressure on unit production costs.
The Chronology of Shift: Physical Media Under Pressure
The tension between digital distribution and physical manufacturing has developed across several distinct phases over the past several years, marked by shifting publisher strategies, pricing adjustments, and hardware transitions.
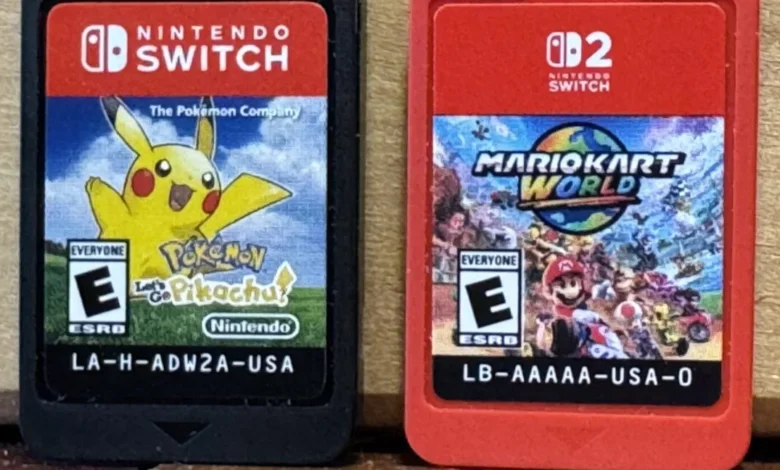
Throughout the life cycle of the original Nintendo Switch, physical cartridges remained a dominant force in retail spaces, beloved by collectors and casual consumers alike for their tangible nature, resale value, and independence from server longevity. Yet, behind the scenes, publishers frequently grappled with the higher baseline costs of manufacturing physical cartridges compared to hosting digital assets on servers. Larger game sizes often necessitated higher-capacity ROM chips, which carried a severe cost penalty that could eat heavily into publisher profit margins—particularly for independent studios and mid-tier publishers.
By late 2025, these underlying financial pressures began to manifest visibly in the marketplace. In December 2025, Japanese publisher Inin Games illuminated the delicate economic calculus of cartridge manufacturing when discussing its release strategy for R-Type Dimensions III. The publisher explicitly noted that its commitment to a full, physical cartridge release was only made viable because the introduction of new, lower-capacity storage cartridge sizes for Nintendo’s hardware ecosystem successfully lowered the cost of producing the physical units. Without these smaller, cost-effective options, the financial risk of a physical release would have been prohibitive.
As the industry moved into early 2026, the economic reality of physical production triggered direct consumer-facing adjustments. In March 2026, Nintendo implemented a controversial pricing strategy, officially starting to charge more for select physical games than for their equivalent digital downloads. This pricing divergence marked a significant break from long-standing retail norms, where physical and digital editions traditionally shared identical launch MSRPs. By shifting the financial burden of physical logistics, manufacturing, and raw material acquisition directly onto the consumer, Nintendo signaled that the era of frictionless physical pricing had come to an end.
Despite these cost-mitigation efforts, supply chain realities caught up with public relations declarations. Just last month, Nintendo executives reiterated their official stance, assuring stakeholders and consumers that the company had no immediate plans to abandon physical game production, explicitly acknowledging how deeply attached the fanbase is to physical cartridges. However, industry observers were quick to contextualize this statement: while the desire to support physical media remains absolute within Nintendo’s corporate strategy, the ability to do so without inflating costs is severely tested by the shrinking roster of ROM chip fabricators.
Supporting Data and Market Dynamics
To understand the broader trajectory of Nintendo’s software distribution, one must examine financial disclosures and market analytics detailing the ongoing migration toward digital platforms.
Market research and financial data from the second calendar quarter of 2026 reveal that digital software sales accounted for 61.5 percent of Nintendo’s total business revenue. This figure represents a steady, incremental increase compared to the corresponding period in the previous year. While a nearly 40 percent physical footprint remains a multi-billion-dollar enterprise that few corporations would abandon lightly, the year-over-year erosion of physical market share underscores a silent, inevitable consumer migration toward digital storefronts.
| Metric / Period | Q2 2025 | Q2 2026 | Trend Analysis |
|---|---|---|---|
| Digital Software Sales Share | ~58.5% | 61.5% | Steady upward migration |
| Physical Software Sales Share | ~41.5% | 38.5% | Gradual contraction |
| ROM Component Availability | Stable baseline | Increasingly constrained | Higher vendor concentration |
| Physical vs. Digital Price Parity | Maintained | Diverged (Physical higher) | Margin protection shift |
This statistical shift introduces a complex economic balancing act. On one hand, as total volume demands for ROM-based cartridges gradually decline in favor of digital downloads, the absolute necessity for massive semiconductor foundry allocations decreases. On the other hand, lower overall manufacturing volumes can occasionally diminish economies of scale, potentially driving up the per-unit cost of the remaining physical cartridges produced.
Financial analysts, including prominent gaming industry watcher Dr. Serkan Toto and independent market strategist David Gibson, have frequently highlighted this duality. Gibson’s observations regarding the 61.5 percent digital milestone suggest that if digital adoption continues along its current upward trajectory, the natural reduction in demand for physical ROM chips could eventually normalize manufacturing pressures. In theory, a smaller, highly dedicated market for physical collectors could sustain itself sustainably, provided that component pricing stabilizes and publishers are willing to accept niche production runs.
Official Responses and Corporate Strategy
Nintendo has historically positioned itself as a champion of traditional play styles, emphasizing the integration of hardware and software design that relies on physical objects—ranging from cardboard Labo kits to dedicated game cards. Executive statements consistently reflect a keen awareness of brand identity. Company leadership has repeatedly stressed that physical game ownership represents a core pillar of consumer trust and accessibility, particularly for younger demographics and regions with less reliable broadband infrastructure.
However, corporate communications must balance nostalgic appeal with fiscal responsibility. By shifting the financial framework—introducing tiered cartridge capacities to help indie publishers, adjusting MSRPs upward for physical SKUs, and leaning into the digital eShop infrastructure—Nintendo is attempting to insulate its profit margins from external component shocks.
Suppliers such as Rohm and Lapis Semiconductor have remained largely tight-lipped regarding specific contractual arrangements with consumer electronics giants, adhering to standard industry confidentiality agreements. Nevertheless, macroeconomic reports from the semiconductor sector indicate that specialized legacy nodes are seeing rationalization across the board. Manufacturers are prioritizing long-term yield optimization over custom low-volume runs, forcing hardware makers to negotiate higher baseline purchase orders or absorb creeping per-unit cost increases.
Broader Impact and Industry Implications
The challenges facing Nintendo’s physical cartridge supply chain carry significant implications for the broader video game industry, signaling the end of an era for traditional retail media.
As Sony continues its aggressive push toward a digital-first ecosystem—exemplified by console revisions lacking integrated disc drives and digital-heavy sales disclosures—and Microsoft similarly prioritizes Game Pass and cloud streaming, Nintendo remains the primary major console manufacturer actively maintaining a robust physical software pipeline at retail. Consequently, the health of Nintendo’s physical supply chain serves as a bellwether for the entire physical game retail sector.
For specialty retailers, game collectors, and second-hand markets, the rising cost of physical production poses structural threats. If publishers are forced to pass higher manufacturing costs onto consumers through elevated physical pricing, casual buyers may be definitively priced out of physical media, accelerating the transition to all-digital libraries. Conversely, higher prices could transform physical cartridges into luxury collector’s items, altering the cultural significance of owning a physical game cartridge from a mainstream standard to a niche enthusiast hobby.
Ultimately, Nintendo’s physical game strategy is limping along precisely because it is caught between two powerful, opposing forces: a fiercely loyal consumer base that demands tangible game ownership, and an industrial semiconductor supply chain that is increasingly unwilling or unable to support legacy manufacturing processes without significant financial premium. How Nintendo balances these economic realities over the coming years will determine whether physical cartridges remain a viable retail staple or become an expensive boutique luxury in an increasingly digitized world.